Avoid filing errors: 7 step UK chart of accounts setup

A correct chart of accounts setup does two jobs at once: it gives you management numbers you can actually act on, and it produces the statutory figures Companies House and HMRC expect. Start by choosing a small, deliberately limited set of accounts, map each one to a statutory heading before you enter a single transaction, and confirm your VAT codes and FRS 105 or FRS 102 classification early.
TL;DR:
A well-structured chart of accounts should use block numbering with gaps for growth and precise account names to facilitate accurate reporting and analysis.
Mapping each nominal code correctly to statutory headings from the start ensures compliance and simplifies year-end reporting, especially for micro-entities under FRS 105.
Starting from a software template, assigning VAT codes early, and building a small, tested core set of accounts reduce rework and discrepancies later.
Regular review and maintenance, including archiving inactive accounts and adding new ones only when necessary, keep the COA relevant and manageable over time.
For multi-currency and multi-entity structures, using a shared master chart with entity-specific tracking codes simplifies consolidation and compliance across jurisdictions.
Table of Contents
What is a chart of accounts and why does its structure matter?
How do software defaults compare for chart of accounts setup?
What Keystone sees when clients get their chart of accounts wrong
Adapting your chart of accounts by industry and business type
Using the chart of accounts for budgeting and financial analysis
How much detail should your chart of accounts actually have?
Handling multi-currency and multi-entity structures in your chart of accounts
What is a chart of accounts and why does its structure matter?
A chart of accounts (COA) is the numbered list of every account your bookkeeping system uses to record transactions. Every entry in your accounting software, from a sales invoice to a fuel receipt, gets tagged to one of these accounts, and those tags eventually roll up into your statutory accounts.
Five categories sit underneath almost every UK chart of accounts, and each one feeds a specific financial statement:
Assets (what you own): cash, debtors, equipment, stock, feeding the balance sheet
Liabilities (what you owe): loans, creditors, VAT payable, also on the balance sheet
Equity: share capital and retained earnings, the residual claim after liabilities
Revenue: sales and other income, the top line of the profit and loss account
Expenses: cost of sales, overheads, wages, everything that reduces profit
A typical UK chart of accounts organises these into conventional nominal code ranges, such as 1000 to 1999 for assets and 4000 to 4999 for revenue. These ranges are conventions, not law. Your software may use entirely different numbering, and that is fine as long as the logic holds. The design principles that matter more than any specific number range are simplicity, room to grow, alignment with your statutory reporting format, and consistency in how you apply codes month after month.
How should I number and name my nominal codes?
Numbering strategy determines whether your COA survives three years of growth or needs a painful rebuild. Block numbering, where each category owns a range of codes, is the standard approach and it is what most UK software templates use by default.
Leave gaps inside each block. If sales sits at 4000 to 4099, do not use 4001, 4002, 4003 consecutively. Space codes out (4000, 4010, 4020) so you can insert a new account later without renumbering everything
Decide digit length once and stick with it. Xero defaults to three-digit codes, while Sage commonly runs four-digit nominal codes. Match whichever convention your software expects
Name accounts precisely. “Office costs” and “Office expenses” as two separate accounts is a classic way to end up with duplicated, meaningless data
Keep control accounts, bank, VAT, and PAYE, in their own reserved codes and never post general transactions to them directly
Pro Tip: Before you assign a single code, list the outputs you actually need, your VAT return, your P&L, your balance sheet, and build accounts backwards from those outputs rather than inventing accounts you think you might need one day.
Steps to create a chart of accounts you can use today
Setting up a workable COA is a sequence, not a single decision. Follow these steps in order and you will avoid most of the rework that comes from rushing the first week of bookkeeping.
Confirm your entity type and reporting standard. A micro-entity reporting under FRS 105 needs a leaner COA than a company preparing full FRS 102 accounts, so decide this before building anything.
Start from a software template rather than a blank sheet. Xero, QuickBooks, and Sage each ship a default UK chart of accounts you can adapt, which is far faster than designing one from scratch.
Assign VAT codes to every account as you go. Leaving this until later is how VAT-registered businesses end up with mismatched returns.
Build a small, tested set of accounts first. Add ten or fifteen core accounts, not eighty. You can always add more once real transactions reveal genuine gaps.
Run sample transactions and reconcile the bank. Post a handful of invoices and bills, then check the numbers land where you expected on your P&L and balance sheet.
Archive anything unused rather than deleting it. This keeps historical reports comparable.
Write down your naming and numbering rules. A one-page document saves the next person, including your accountant, hours of guesswork.
Mapping your chart of accounts to statutory reporting
Companies House and the Financial Reporting Council expect your accounts to land in specific statutory line items: turnover, cost of sales, creditors due within one year, creditors due after one year, share capital, and retained earnings. Your COA needs to feed these categories cleanly, which means every nominal code should trace back to only one statutory heading.
Group all sales-related revenue accounts so they consolidate to a single turnover figure
Split creditors into current and non-current ranges early, rather than reclassifying at year-end
Keep share capital and retained earnings in dedicated equity codes, never mixed with reserves or director loans
If your business qualifies as a micro-entity, FRS 105 sets specific thresholds: turnover under £1,000,000, a balance sheet under £500,000, and fewer than 10 employees, effective from April 2025. Falling under these limits lets you file a simplified balance sheet, but your COA still has to capture every account needed for VAT and tax reporting, so “simplified” never means “sparse”. Before year-end, run a quick check: does every nominal account map to a line on your draft statutory accounts, and does nothing sit orphaned in a miscellaneous code?
How do software defaults compare for chart of accounts setup?
Every major UK platform ships a workable starting chart, but the defaults differ enough that adopting one blind causes problems later. Xero’s standard UK chart uses three-digit codes and a fairly fixed structure, QuickBooks allows fuller customisation of both codes and categories, and Sage typically runs four-digit nominal codes with more granular default categories.
Before you enter live transactions on any platform, check:
Whether the default template reflects UK Companies Act formats, not a US or IFRS layout that has crept in through an international template
That VAT codes attach correctly to each account, since Making Tax Digital requires VAT-registered businesses to file through MTD-compatible software
Whether the default digit length matches your reporting needs, particularly if you plan to add cost centres or departments later
Reviewing and maintaining your chart of accounts over time
A COA is not a one-off project. Review it at least once a year, ideally just before your accounting year-end, and treat three actions as routine: archive accounts that saw no activity, add new ones only when a genuinely new revenue stream or cost category appears, and reclassify anything that has been sitting in the wrong statutory bucket.
Pull a trial balance and flag every account with zero or near-zero activity for the year
Archive those accounts rather than deleting them, so prior-year comparatives still reconcile
Route any new account request through a single owner, usually your bookkeeper or finance lead, before it goes live
Pro Tip: Use cost centres or tracking categories in your software instead of creating near-duplicate accounts for each department or project. It keeps the GL code structure small while still giving you the detail you need in reports.
What Keystone sees when clients get their chart of accounts wrong
Working with founders across sectors, three priorities come up on nearly every engagement: keep the structure simple, map it correctly to statutory headings from the outset, and get VAT coding right before Making Tax Digital exposes the gaps. One recurring pattern is a client who inherited an overgrown COA from a previous bookkeeper, sometimes 150 accounts for a business with three revenue lines. Reorganising it into a dozen core accounts, properly mapped, resolved a filing discrepancy that had been quietly distorting their creditors figure for two years. For deeper reading on preparing the statutory accounts your COA ultimately feeds, see Keystone’s statutory accounts preparation guide.
Adapting your chart of accounts by industry and business type
A retailer’s chart of accounts looks nothing like a software company’s, and forcing one template onto the wrong business model is a common source of unusable reports. A retail or ecommerce business needs granular cost of sales accounts, separate codes for platform fees, shipping, and returns, because gross margin analysis depends on seeing these apart rather than lumped into one expense line. A detailed ecommerce COA breakdown shows how quickly this can expand once you factor in multiple sales channels.
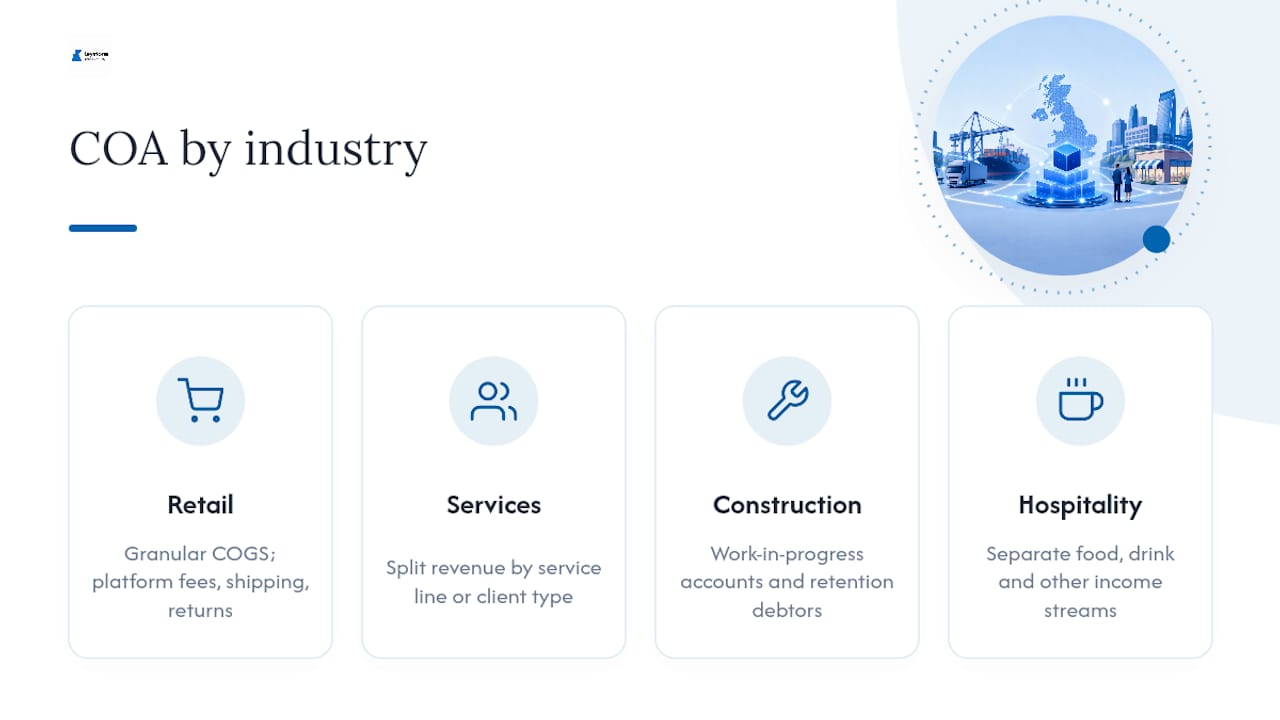
A services business, by contrast, rarely needs cost of sales accounts at all beyond subcontractor costs, but benefits from splitting revenue by service line or client type if that distinction drives decisions. A construction or project-based business often needs work-in-progress accounts and retention debtors that a services firm would never touch. Hospitality businesses typically separate food, drink, and other income streams because margins differ wildly between them.
The mistake to avoid is copying a generic template and leaving in accounts your business will never use, alongside missing the two or three accounts your specific model actually needs. Start from your own revenue streams and cost drivers, not from what a template assumes is standard. If you run a single trading activity with straightforward costs, resist the urge to add accounts “just in case”. If you run multiple distinct activities, whether that is a shop with an online arm or a consultancy with a product line, build separate revenue and cost blocks for each from the start, because retrofitting that split after a year of mixed data is far harder than starting clean.
Using the chart of accounts for budgeting and financial analysis
A chart of accounts only earns its keep once it starts driving decisions, and that means connecting it directly to your budget and management reports, not just your year-end filing. If your budget is built in a spreadsheet with categories that do not match your COA line for line, every month-end comparison becomes a manual reconciliation exercise rather than a five-minute check.
Build your budget using the exact same account structure as your COA, down to the code level where practical. This means when you pull a profit and loss report from your software, it lines up directly against budgeted figures with no remapping required. It also means that when you add a new account mid-year, you update the budget template at the same time, rather than discovering a gap three months later.
Granularity matters here too. If your COA lumps all marketing spend into one account but you want to compare paid advertising against content costs in your budget, you need those as separate accounts, not a single line you try to split later using memory and guesswork. The same logic applies to any cost you actively manage: if you are watching it closely enough to budget for it, it deserves its own account or, at minimum, its own tracking category. Reports built this way become genuinely useful for spotting variance early, rather than a formality you glance at after the numbers are already locked.
How much detail should your chart of accounts actually have?
The right level of detail sits between two failure modes: an account list so sparse it hides useful information, and one so granular that nobody can read a report without a headache. Neither extreme serves a founder trying to understand their own numbers.
A useful rule of thumb is that every account should represent a decision you might actually make. If knowing the split between two expense types would never change what you do, they probably belong in one account. If it would, split them. This is why a business spending £200 a month on stationery does not need three accounts for pens, paper, and printer ink, but a business spending £50,000 a year on subcontractors across three trades might genuinely benefit from splitting that cost by trade.
Software choice affects this too. A platform with strong tracking categories or cost centres, such as most mid-tier UK packages, lets you keep the core COA lean while still slicing reports by department, project, or location using tags rather than extra accounts. This is almost always the better route than multiplying nominal codes, because it keeps your statutory mapping clean while still giving you the analytical detail you want in management reports. Over-granularity is, in practice, more common than under-granularity among small businesses, usually because someone added a new account for every new supplier or project rather than reusing existing categories with better descriptions.
Handling multi-currency and multi-entity structures in your chart of accounts
Businesses trading internationally or operating through more than one legal entity need a COA that can absorb that complexity without losing statutory accuracy for each entity individually. For multi-currency operations, most UK accounting platforms handle currency conversion at the transaction level rather than requiring separate accounts per currency, but you still need dedicated accounts for realised and unrealised foreign exchange gains and losses, since these need to be visible and reportable separately from operating income.
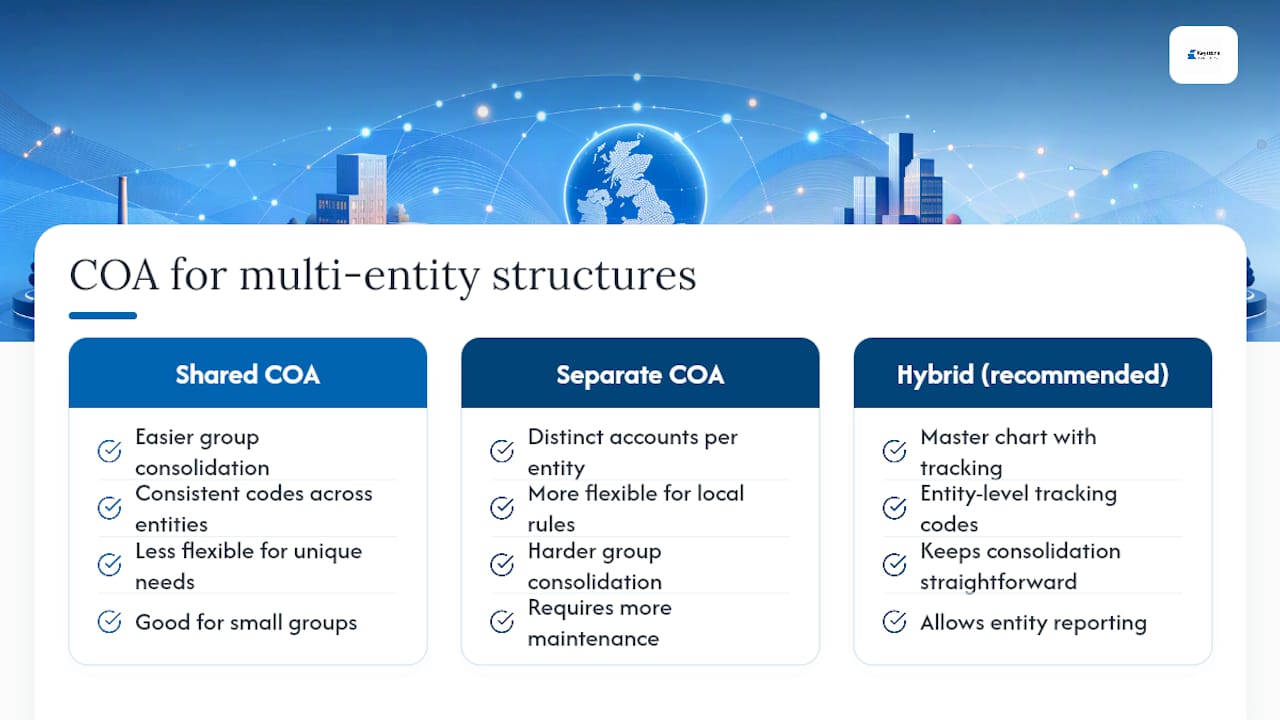
Multi-entity structures raise a different question: whether to run one shared chart of accounts across all entities or a distinct one per entity. A shared structure, using consistent codes across a parent company and its subsidiaries, makes group consolidation far easier because the same code always means the same thing regardless of which entity you are looking at. The trade-off is less flexibility if one entity has genuinely different reporting needs, say a UK trading company alongside an overseas subsidiary reporting under different local rules.
For most small groups, a shared master chart of accounts with entity-specific tracking codes layered on top works better than maintaining entirely separate charts. It keeps consolidated reporting straightforward while still letting you pull entity-level figures when needed. If your structure involves genuinely different statutory frameworks between entities, get this mapped properly before your first year-end rather than after, since retrofitting a consolidation structure onto historical data is considerably more work than building it in from the start.
A quick word on where founders go wrong
The mistakes I see most often are not exotic. They are over-granular expense accounts nobody maintains, control accounts used for general postings by mistake, and VAT codes left as defaults that do not match the transaction type. None of these are hard to fix early, but they compound fast once a year of data sits on top of them. If your VAT position is complex, you are running multiple entities, or an audit is on the horizon, bring in an accountant before you build the COA, not after.
— Shoaib
Let Keystone set up or review your chart of accounts
An effective approach is to map your chart of accounts to your statutory reporting requirements from the first conversation, so the structure you build early still works cleanly at year-end.
[
](www.keystonefa.co.uk)
Our services cover the whole chain this article has walked through, from initial COA setup and bookkeeping onboarding through to statutory accounts preparation and audit readiness checks, so you are not stitching together advice from five different sources. A typical engagement starts with a short discovery call to understand your entity structure, VAT position, and reporting standard, then moves into either advisory support or a fully done-for-you setup, depending on how hands-on you want to be. If your accounting software setup needs attention alongside your chart of accounts, our software setup guide covers the practical steps in more detail. Fees for ongoing support start at £99 to £199 per month depending on scope, detailed on our services page. If your year-end is approaching, book a short review with Keystone now while there is still time to fix mapping issues before they hit your filing.
Sources
For thresholds and statutory formats, gov.uk’s guidance on annual company requirements covers FRS 105 eligibility in full. For platform-specific setup steps, consult your software’s own help pages, and for broader firm-level context on accounting practice, see Keystone’s insights and updates.
FAQ
What are the five basic categories in a chart of accounts?
The five core categories are assets, liabilities, equity, revenue, and expenses. Assets, liabilities, and equity feed the balance sheet, while revenue and expenses feed the profit and loss account, and most UK software groups them using conventional nominal code ranges such as 1000 to 1999 for assets.
How should a chart of accounts be organised?
Organise it in blocks, one range of codes per category, with gaps left inside each block for future accounts. Keep control accounts like VAT and PAYE separate from general trading accounts, and align the overall structure with the statutory headings your accounts will eventually need to produce.
What is the typical format of a UK chart of accounts?
A typical format lists accounts numerically by category, starting with assets and working through to expenses, using either three-digit or four-digit nominal codes depending on the software. Xero and Sage both ship with default templates that follow this structure, which you then adapt to your business.
What should be in my chart of accounts?
At minimum, include accounts covering your actual revenue streams, direct costs, overheads, bank and VAT control accounts, and the equity accounts required for your entity type. Avoid adding accounts you do not yet have a transaction for. If you are unsure what your specific business needs, KeystoneFA can review your draft structure as part of a setup engagement.
Do I need a different chart of accounts for FRS 105 versus FRS 102?
Not a fundamentally different one, but a leaner one. FRS 105 micro-entities can use a simplified balance sheet if they meet the thresholds, but the underlying COA still needs to capture full VAT and tax detail.
Recommended